Only the datapoints that apply to you.
Your material topics decide what you report, so your team collects what the statement needs and nothing more.
Double materiality first, then only the ESRS disclosures that follow from it, with the evidence behind every item.
Which ESRS topics are material for us?
Three topics are material for you. Climate change scores highest, on impact and on financial risk.
Not material: E4 Biodiversity. None of your sites is near a protected area.
Your material topics decide what you report, so your team collects what the statement needs and nothing more.
Each entity answers its own part, and the answers roll up into one statement, with the EU Taxonomy alongside.
Score every impact, risk and opportunity, see which ESRS topics are material, and keep the reasoning your assurer will ask for.
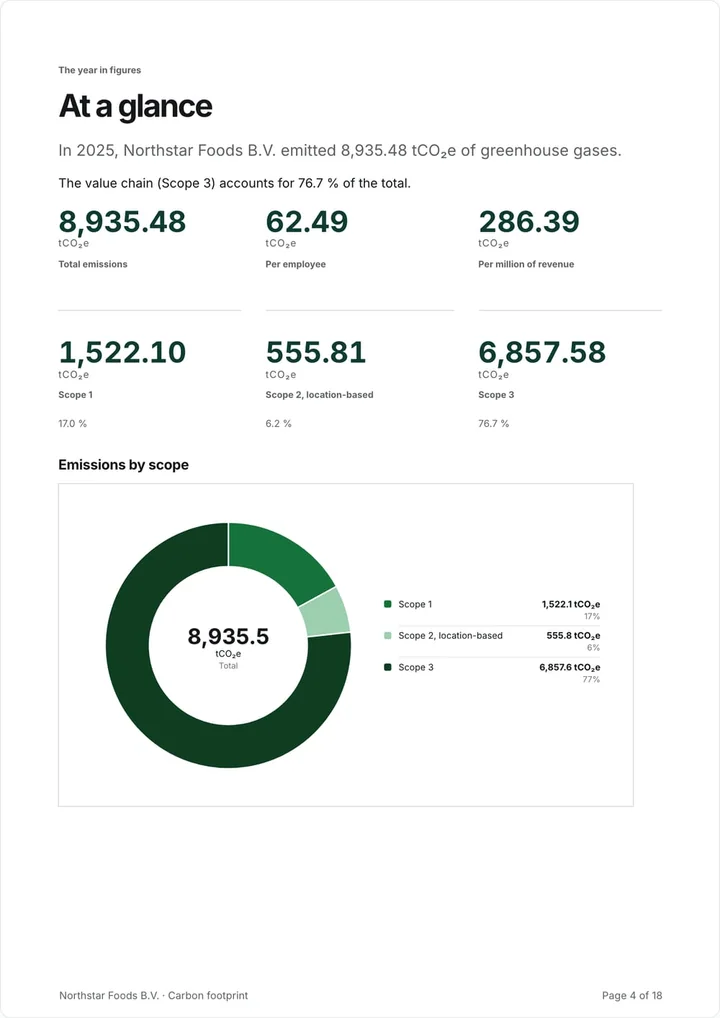
With Carbon accounting, your approved footprint fills the E1 emissions disclosures, so you calculate once.
Every figure traces back to its source, with the checks your assurer runs already done.
Prices in EUR, excluding VAT. Plans and SSO are billed annually.
Find answers to your questions right here, and contact us if you cannot find what you are looking for.
No. Your double materiality assessment decides which topics are material, and only those disclosures are asked for, with the phase-in reliefs you qualify for.
Impacts, risks and opportunities are suggested for your activities. You score them on impact and on financial materiality and approve them, and the material topics decide what you report.
Yes. Each entity answers its own part, and the answers roll up into one statement.
Your assurer gets their own access, with the evidence and queries on every item, so the review happens in one place instead of over email.
Yes, when you have Carbon accounting. Your approved footprint fills the E1 emissions disclosures, so you calculate once.
Yes. Your eligible and aligned activities are part of the statement.